


Polyether Market: Winter Has Arrived—Is Spring Still Far Off?
Release time:
22 Feb,2020
At the start of 2020, the Phase One economic and trade agreement between China and the United States was signed, boosting market confidence across the board; however, the escalating COVID-19 pandemic caught everyone off guard.
The short-term direct impacts of the pandemic are evident and manifest in four specific areas:
First, governments across many parts of the country have issued regulations extending the Spring Festival holiday, prohibiting enterprises and factories from resuming work before February 9 (with some severely affected areas extending this to February 14). This has constrained production.
Second, traffic restrictions have been imposed on transportation routes in many parts of the country, hindering the movement of goods.
Third, consumer spending is currently constrained to essential, basic needs, and many malls and stores remain closed, preventing any recovery in consumption.
Fourth, in terms of imports and exports, the WHO declared this outbreak a PHEIC, and multiple countries imposed entry restrictions on flights and ships originating from China.
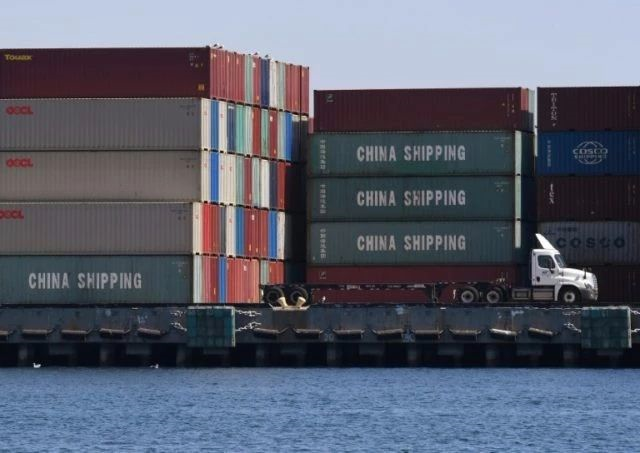
For the polyurethane industry, domestic demand remains weak as end‑user consumption struggles to pick up. Downstream foam manufacturers have delayed resuming operations, disrupting normal production and leading to rising inventories, which in turn dampens demand for upstream raw materials. Meanwhile, transportation restrictions in many regions are hindering shipments, preventing even modest demand from being met smoothly. Raw material producers are seeing mounting inventory pressures, cutting operating rates, and in some cases halting production altogether. Export trade has also been adversely affected in the short term.
Overall, the longer the pandemic drags on, the greater its negative impact; however, there is no need for excessive pessimism.
Looking back at the 2003 SARS outbreak, China’s economy was most affected in the second quarter of that year, with GDP growth rates of 11.1%, 9.1%, 10%, and 10% across the four quarters. However, SARS did not alter the underlying upward trend of the Chinese economy at the time; from 2001 to 2005, real GDP grew by 8.3%, 9.1%, 10%, 10.1%, and 11.4%, respectively.
In response to this outbreak, the government has also been actively implementing measures. For example, on the first day of trading, the People’s Bank of China injected 1.2 trillion yuan in liquidity through reverse repos. Additionally, five ministries and commissions have instructed financial institutions not to arbitrarily recall loans, cut off credit, or suppress lending to sectors severely affected by the epidemic, as well as to enterprises with growth potential but temporarily facing difficulties due to the pandemic—particularly small and micro businesses. For enterprises severely impacted by the epidemic that are struggling to repay maturing loans, loan extensions or renewals may be granted. Furthermore, by appropriately lowering loan interest rates and increasing credit and medium- to long-term loans, authorities aim to support affected businesses in overcoming the adverse impacts of the pandemic.
In the author’s view, if the pandemic can be brought under effective control in the short term, the economic situation may stabilize in the second quarter and then experience a modest recovery.

From a micro‑level polyether market perspective, market sources indicate that, due to restrictions on domestic goods exports, polyether prices have begun to rise in regions such as Southeast Asia. Additionally, certain Chinese‑produced polyether products hold significant shares in overseas markets; some industry participants suggest that export constraints could further tighten supply of these products. Meanwhile, if the domestic economy recovers in the second quarter, higher overseas polyether prices and a widening demand gap could both spur a rebound in China’s polyether sector.
At present, China’s economic situation is indeed in a severe winter, but with winter here, spring cannot be far behind.
To borrow a phrase from IMF Managing Director Kristalina Georgieva in a video released yesterday: “We are fully confident in the resilience of China’s economy.”


Quick Navigation
Contact Us
No. 428, Jinbai Road, Jinshan Industrial Zone, Shanghai, China

WeChat Video Channels

WeChat Official Account

TikTok account